Wind · hail · storm
Roof estimates
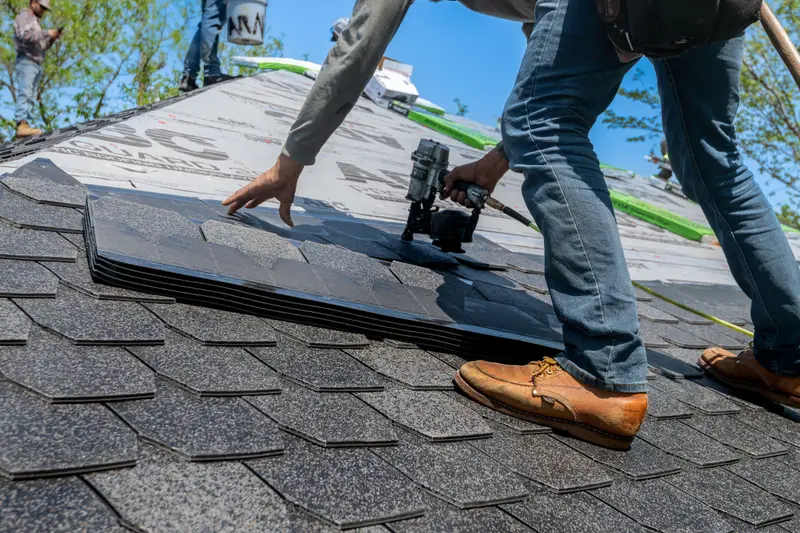
Full roof scopes and supplements, tear-off to ridge, with the code sections and manufacturer specs attached to every added line.
Roof estimates
 Knoxville, TN · Insurance estimates
Roof, mitigation, exterior and commercial estimates, built from photos, code and manufacturer specs, for contractors who already have a claim open.
Our average supplement return. Across the files we write, the approved amount comes back 25 percent or more above the carrier's first estimate.
On the carrier side first. Zachary spent over a decade in claims, including a catastrophe response team and complex large loss litigation, before founding the firm in 2022.
Licensed and certified. PA, CPCU and SPPA, licensed in five states, residential and commercial.
That 25 percent is our own average across completed files, not a promise about yours. Every claim turns on its own policy, damage and documentation.
Carrier-trainedWe know how a carrier builds a scope, because Zachary spent over a decade building them.
A first insurance estimate is written fast. Drip edge, flashing, code upgrades, steep charges. They get left off. We find them, prove them, and file them.
Not every claim needs one. Most of the contractors we work with have a claim already open and a carrier estimate that is short a few thousand dollars. They do not want representation. They want the supplement written properly, with the proof attached. That is the whole job.
If a claim genuinely needs a licensed public adjuster, we will tell you plainly and point you at one. That is a separate, regulated service and it is not what this company sells.
This is what a roof supplement looks like on paper. The carrier’s lines stay. What’s missing gets added, each with the code section, spec or photo that requires it.
Illustrative example. Quantities vary by job; no real claim shown.
From a single roof to a commercial complex. Every file gets the same checklist, the same documentation, the same follow-through.
Full roof scopes and supplements, tear-off to ridge, with the code sections and manufacturer specs attached to every added line.
Roof estimatesWater and fire mitigation scopes built from your readings, drying logs and photos, so the emergency work gets paid like it was done.
Mitigation estimatesSiding, gutters, fascia and windows, the exterior items that get left off a roof-only scope.
Exterior estimatesLarger, more technical scopes for commercial property, membrane systems, edge metal, rooftop units and access.
Commercial estimatesTwo estimates that don’t agree? We line them up item by item and show you exactly where, and why, they differ.
Estimate comparisonPhotographs from claims we have handled. Readings, annotations and measurements taken on site, because an adjuster approves what is documented, not what is described.
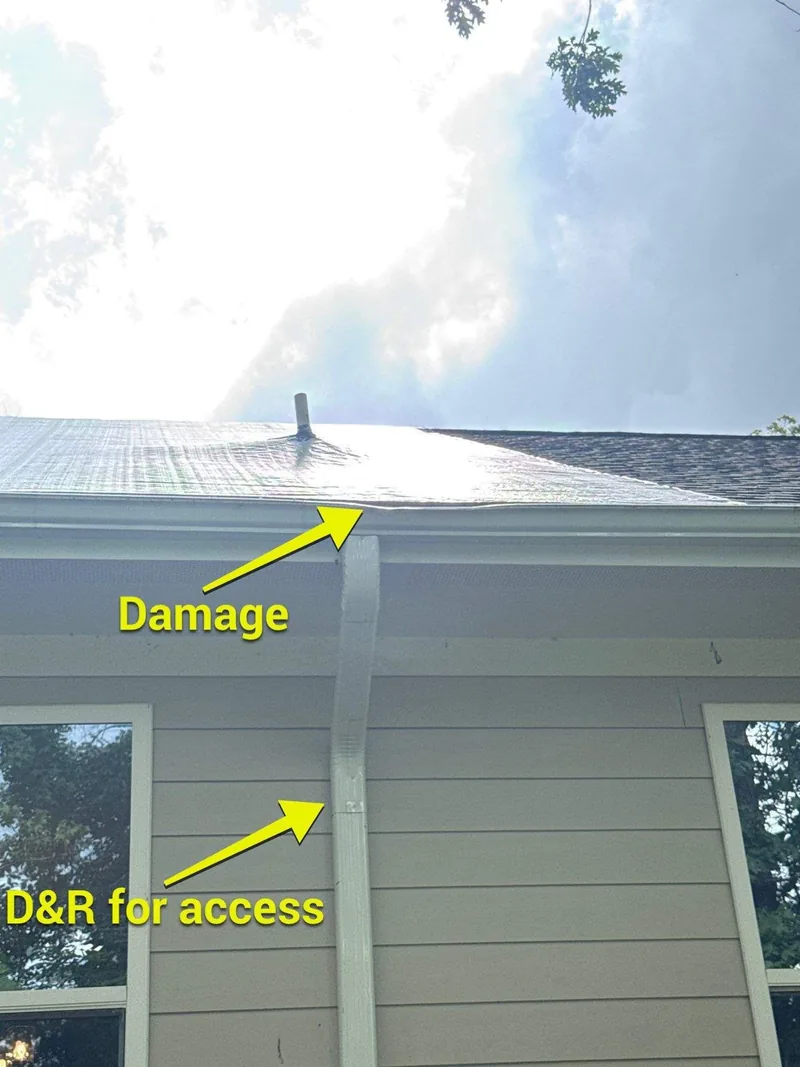
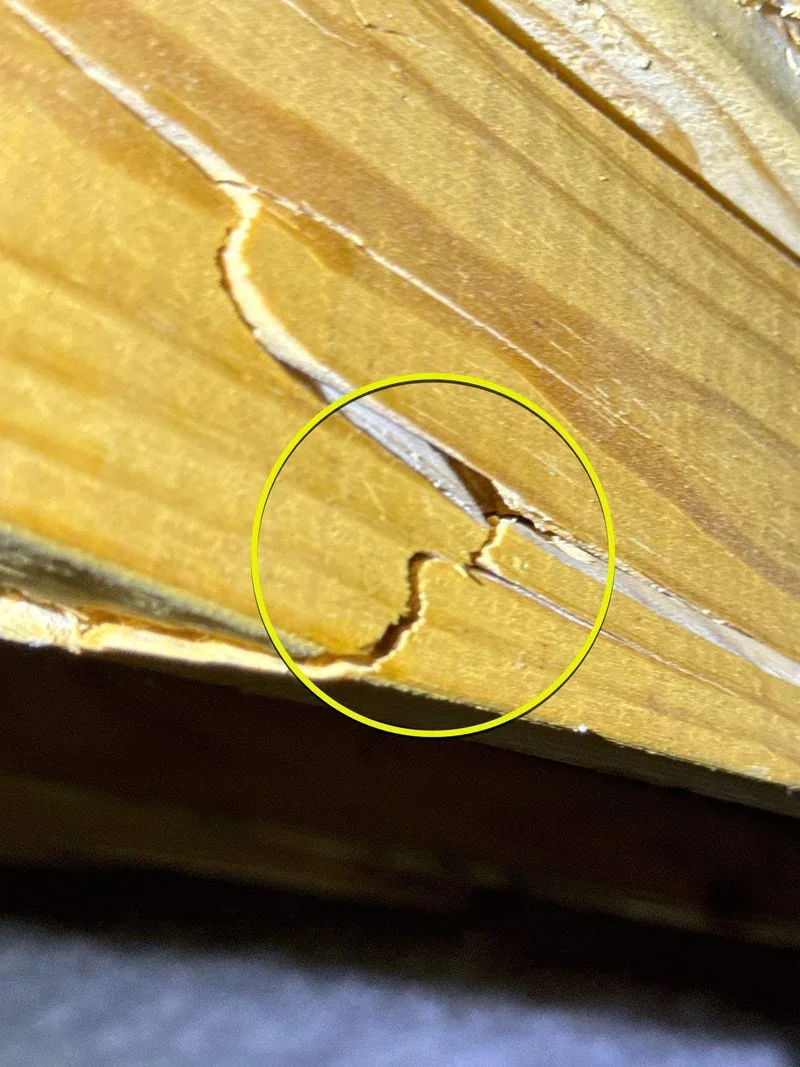
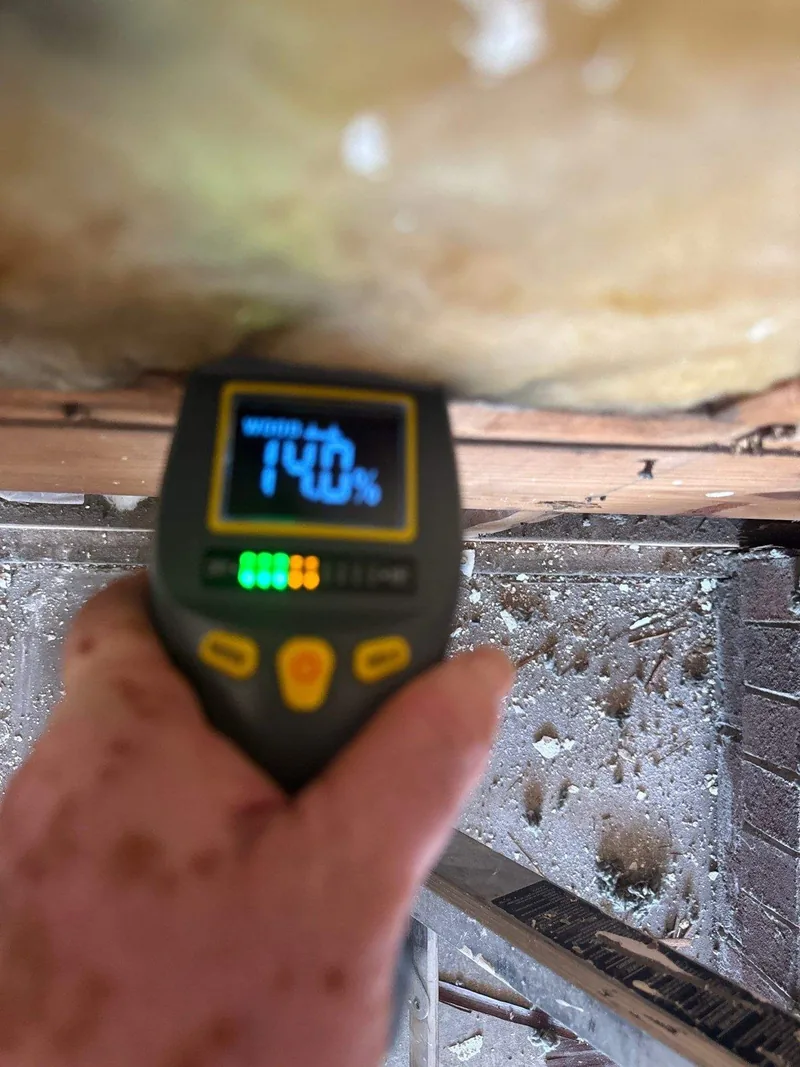
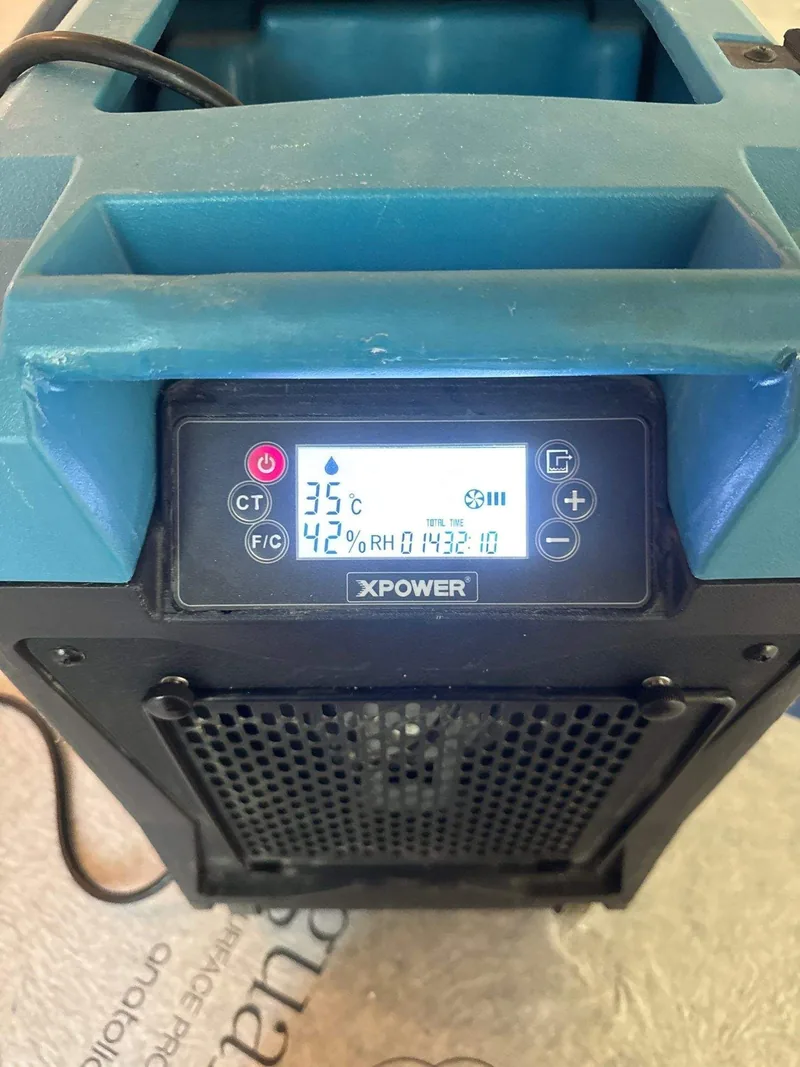
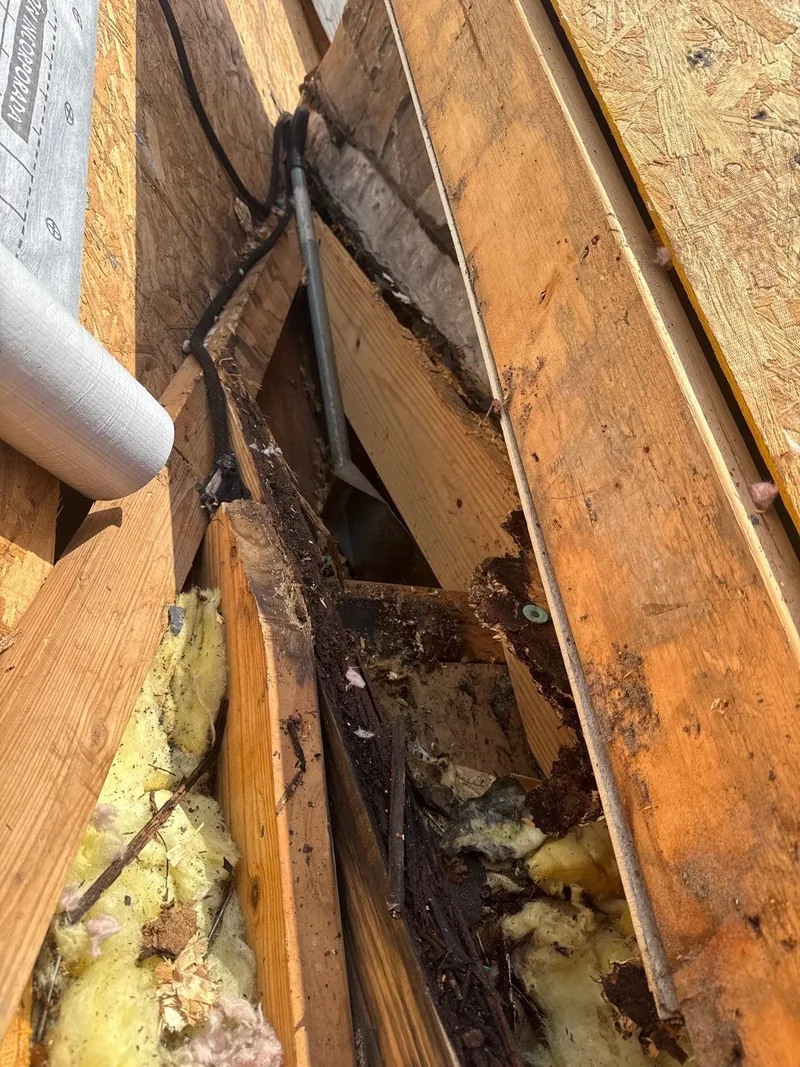
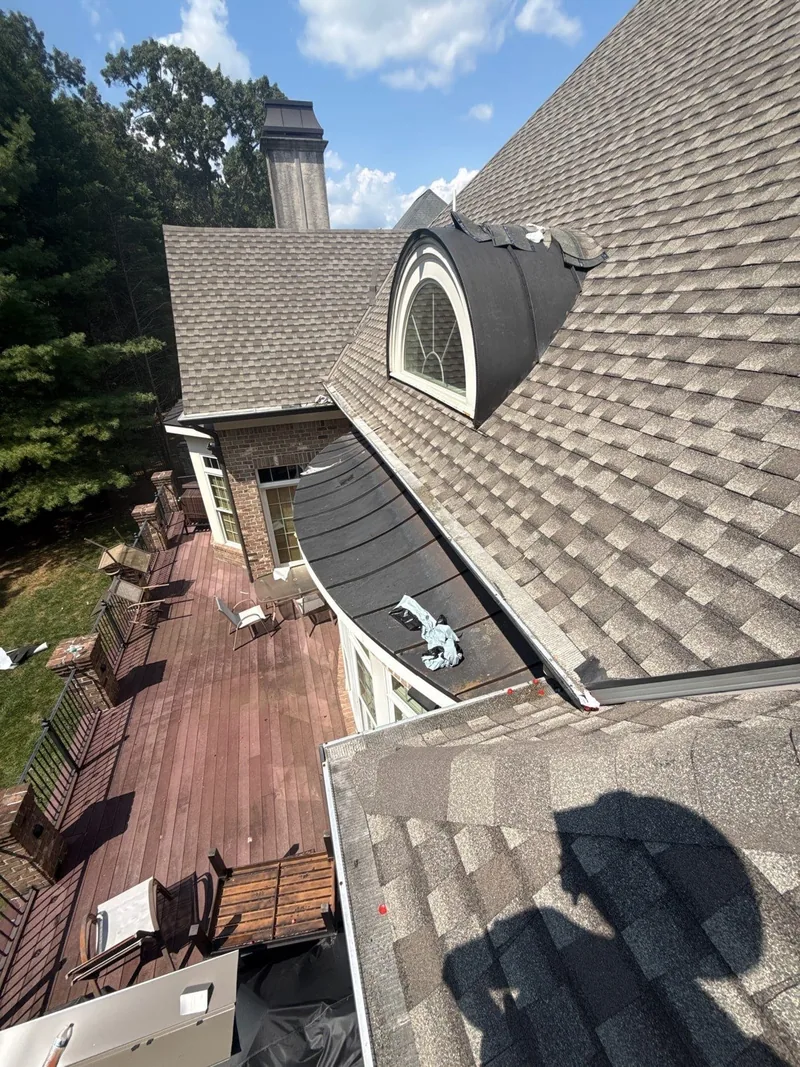
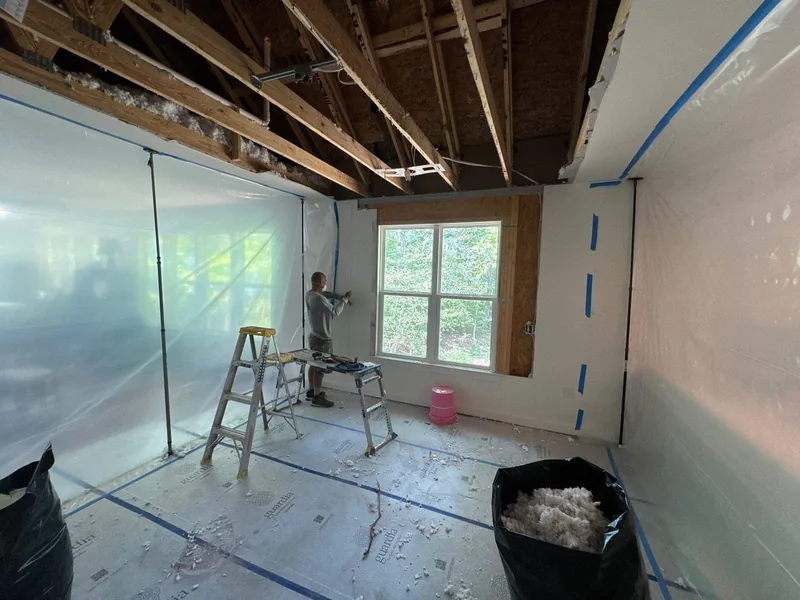
Real files from work we have completed. Addresses, documents, faces and customer details are kept out of every frame.
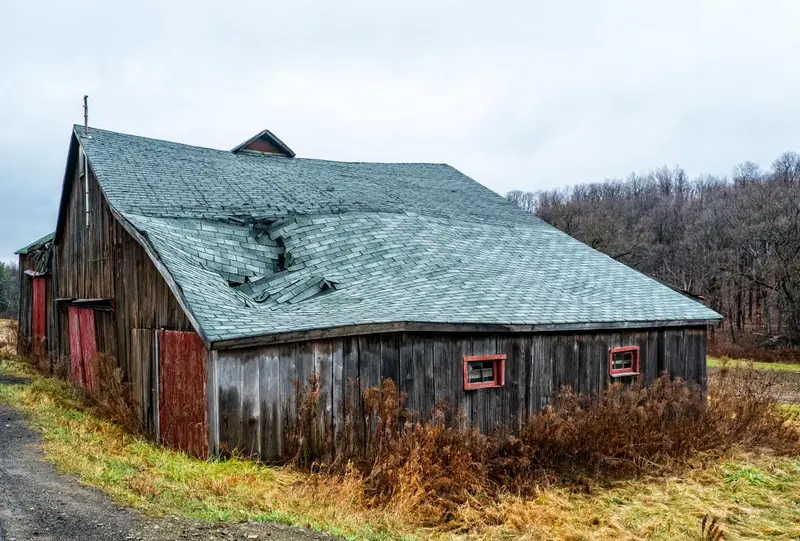
Hail, wind, water, fire. The loss is easy to see. Getting every item of it onto the estimate is the work.
We walk through a few of your files and show you which photos and documents to capture on every job.
Our estimators write it with everything from the inspection, photos, code docs, permits and manufacturer specs.
Questions come back and scopes change. We revise the estimate and re-document it until nothing is left outstanding.
The updated insurance approval comes back, the repairs get done, and payment comes faster.
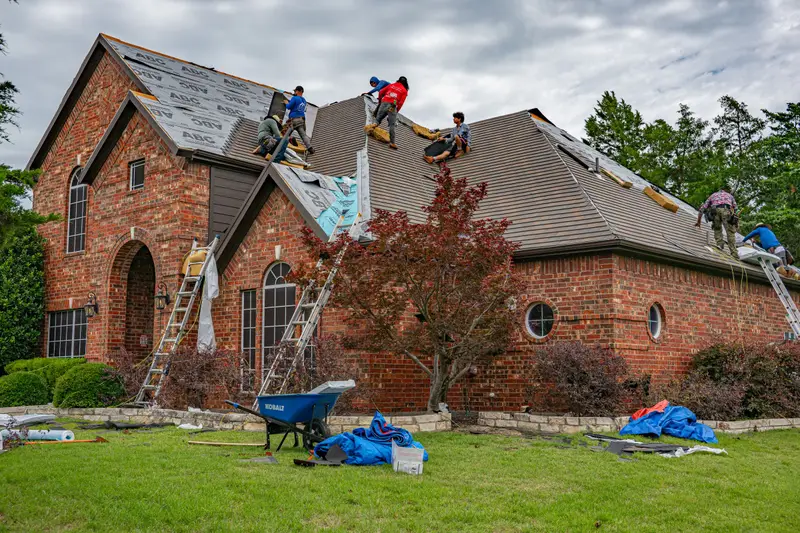
You should be walking projects, running subs and selling, not on hold with a carrier. Get the right photos on site and hand us the rest.
AccuLynxJobNimbusRoof LinkCompanyCamContractors Cloud
Send us one file and pay for one file. Run steady volume and we will price the whole pipeline as a flat monthly fee, commercial claims included.
Send one claim or send one a month. You pay for the file we write, and you know the number before we start.
Running a consistent number of claims a month? We will quote a flat monthly rate for the whole pipeline instead of pricing each file. The more volume you run, the better that rate gets.
Low-slope and membrane systems, multi-building sites, rooftop units and access. Bigger scopes with more line items, priced on the file after we have seen it.
Every quote is given before any work starts. Tell us roughly how many claims a month you run and we will put a number on it.
You sold the job, the loss is covered, and the carrier’s estimate does not pay for the work the job actually needs. You do not need a public adjuster for that. You need the supplement written, documented and filed correctly.
“You can really tell this company is the real deal, the owner and operator has over a decade of claims experience and that showed through each step of the process when working with Insurance Supplement Solutions. You are in good hands with this company.”
“Exception Service!! Was able to get more things covered that insurance overlooked or just flat out missed. Luckily Zach and his crew was able to spot them & get things fixed correctly! THANK YOU SO MUCH ZACH!!”
“Very professional company. Very spot on and accurate. Attention to detail with these guys are incredible”
We don’t invoice for work that isn’t being done, or for inflationary items that have no business in the quote.
We teach contractors to work with the assigned adjuster, and we build a good working relationship with adjusters ourselves.
We put the highest attention on our clients’ reputation in the marketplace. An honest file is a faster file.

Your supplement is written by someone who spent over a decade deciding claims from the other side of the table.
Zachary began his insurance career after serving in the United States Marine Corps. He built his claims background on a catastrophe response team for American Family Insurance, travelling the country for wildfires, hurricanes, tornadoes, floods and mudslides, then worked complex large loss litigation on cases settled at state, circuit and appellate level.
He founded Insurance Supplement Solutions and Holcomb Public Adjusting in 2022, after seeing the same gap from both sides: contractors unsure how the supplement process works, and homeowners missing steps that cost them time and money.
Your story becomes our passion. Results matter. People matter.Zachary Holcomb, President
Supplements are built from your photos and documents, so the job site doesn’t have to be next door. Call and we’ll talk through your files.
Roofing companies and contractors doing insurance work, and property owners who want an estimate checked.
The insurance company’s estimate, your photos from the property, and any documents you already have. On your first files we walk through our photo and document checklist with you, so you know what to capture on site.
No. We don’t invoice for work that isn’t being done, or for inflationary items that have no business being in the quote. Every added line is backed by a photo, a code section or a manufacturer spec.
Yes. Our team follows up with the carrier to get updated scopes and answer their questions about the supplement, and we work with the assigned adjuster rather than around them.
Wind and hail, hurricanes, tornadoes, plumbing and water losses, and fire losses, on residential and commercial property.
We work alongside the tools contractors already use, including AccuLynx, JobNimbus, Roof Link, CompanyCam and Contractors Cloud.
Call Zach, or send the carrier’s estimate and your photos. We’ll tell you what we see.
Tell us what you’re working on. We’ll call you back and let you know how we can help.